Consider a hypothetical borrower, Priya, who wants $15,000 to replace an old HVAC system and pay off a lingering medical bill. She has a 740 credit score, a checking account at U.S. Bank, and a Wells Fargo credit card she opened eight months ago. She narrows her list to three big banks.
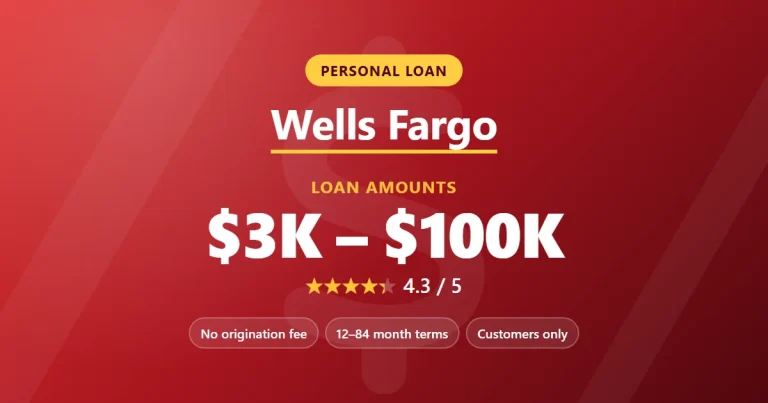
Wells Fargo is out for now: it lends only to customers of at least 12 months, and her relationship there is too new. Citi has a tight APR range but caps most applicants at $30,000, which is fine for her. U.S. Bank, where she already has checking, could fund her loan the same day she signs. That convenience, plus the absence of an origination fee, is the core of what U.S. Bank offers. Here is how it holds up in 2026.
The terms
As of September 14, 2026, U.S. Bank’s fixed APRs ranged from 9.24% to 24.99%, depending on credit score, loan amount, loan purpose, term and whether you choose autopay. What you can borrow depends on whether you’re already a client:
- Current U.S. Bank clients: $1,000 to $50,000, with terms of 12 to 84 months
- Non-clients: up to $25,000, with terms up to 60 months
There’s no origination fee and no prepayment penalty. Checking your rate is a soft credit check; submitting the application pulls your full credit report. You can apply with a joint applicant, whose income and credit are considered too, and no collateral is required.
The bottom of the APR range comes with a long list of conditions: a loan of $10,000 or more, a 12- to 36-month term, a credit score of 800 or higher, a home improvement purpose and autopay from a U.S. Bank personal checking or savings account. Few borrowers will check every box. Plan on something above the floor.
U.S. Bank’s sample: a $10,000 loan at 12.60% APR over 36 months works out to $335.02 a month.
Same-day funding, with conditions
This is the headline feature. If you sign your loan note by 9 p.m. Eastern on a business day and send the money to a U.S. Bank personal checking or savings account (including a Smartly account), you may get funds the same day. U.S. Bank says same-day funding isn’t guaranteed. Sending funds to an account at another bank requires verification and takes one to four business days.
For Priya, with checking already in place, that means her contractor could be paid almost immediately. A non-client would wait a few days, which is still quick by industry standards.
Pros and cons
What works:
- No origination fee, so the full loan reaches you
- Same-day funding for eligible clients
- Open to non-clients, unlike some big-bank loans
- Terms up to 84 months for clients, and amounts as low as $1,000
- Joint applicants allowed
- APR ceiling of 24.99%, well below the 35.99% common at online lenders
What doesn’t:
- Non-clients are capped at $25,000 and 60 months
- The lowest rate requires an 800+ score and a home improvement purpose
- Not every loan program is available in every state
- Same-day funding only works with a U.S. Bank deposit account
JustMobs rating: 4.2/5. A well-rounded bank loan that rewards existing customers without locking everyone else out.
How it compares with Wells Fargo and Citi
Against the Wells Fargo personal loan, U.S. Bank trades a slightly higher rate floor and a smaller maximum for broader access. Wells Fargo’s range starts at 6.74% and its loans go to $100,000, but you must have been a customer for a year. U.S. Bank will consider applicants with no relationship at all.
Against the Citi personal loan, the picture is different. Citi’s APR range (10.24% to 18.49% as of late September 2026) has a much lower ceiling, and it charges no late fees either. If your credit is good, Citi may price you lower. If your credit is fair, U.S. Bank’s wider range may mean an approval where Citi declines. U.S. Bank also offers longer terms, up to 84 months for clients versus Citi’s general 12 to 60.
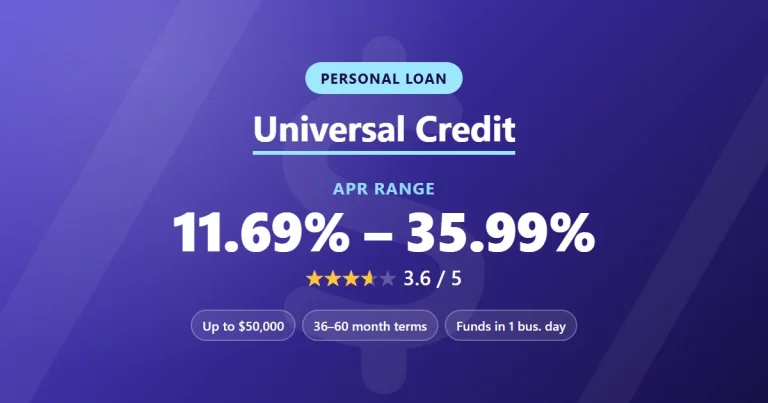
For borrowers who don’t qualify at a bank, online lenders such as Universal Credit accept lower credit scores but charge origination fees.
Tips for getting the best offer
- Check your rate before you apply. It’s a soft pull, so there’s no downside.
- Set up autopay from a U.S. Bank account. It’s part of what earns the lowest pricing, though U.S. Bank says autopay and an account aren’t required for approval.
- Consider the term carefully. The lowest rates apply to 12- to 36-month terms. A longer term lowers the payment but raises total interest.
- Look at your credit report first. U.S. Bank weighs your score, debt-to-income ratio and credit history. Errors can cost you; you can review your reports free at AnnualCreditReport.com.
- Add a joint applicant if it helps. A co-applicant with strong income can improve your offer, but they share responsibility for the debt.
Who should look elsewhere
If your credit is fair or your debt-to-income ratio is high, U.S. Bank’s underwriting may be a tough fit. Banks generally lend to lower-risk borrowers, and the 24.99% ceiling reflects that. A credit union or a fair-credit online lender may be more realistic, though you’ll likely pay an origination fee there.
Non-clients who need more than $25,000 or a term longer than five years should also look elsewhere, or consider whether opening a U.S. Bank account first makes sense for them. And if you’re consolidating credit card debt, keep in mind the Consumer Financial Protection Bureau’s warning that a lower monthly payment over a longer term can cost more overall. The loan only helps if the cards don’t fill back up.
The bottom line
U.S. Bank’s personal loan is a strong pick for its own clients, who get access to $50,000, terms up to seven years and same-day funding with no origination fee. Non-clients can still borrow up to $25,000, which makes it one of the more accessible big-bank loans. The rate floor is reserved for a narrow slice of borrowers, so compare your actual offer with at least one other bank or credit union.
You can check your rate on U.S. Bank’s personal loan page. Rates and terms are as of 2026 and are subject to change without notice.