Start with the rule that decides everything: Wells Fargo personal loans are offered only to existing Wells Fargo customers, and you must have been a customer for at least 12 months. If you opened your first Wells Fargo account last spring, you can’t apply yet. If you don’t bank there at all, opening a checking account today won’t get you a loan this year.
For people who clear that bar, this is one of the better big-bank personal loans available in 2026. The rates are competitive, the fees are minimal and the loan sizes are large.
Wells Fargo personal loans at a glance
| Feature | Details (as of 2026) |
|---|---|
| APR range | 6.74% to 26.74%, including a 0.25% relationship discount (rates as of July 10, 2026) |
| Loan amounts | $3,000 to $100,000 |
| Terms | 12, 24, 36, 48, 60, 72 or 84 months |
| Origination fee | None |
| Closing fee / prepayment penalty | None / none (late fees may apply) |
| Rate check | Soft pull; full application is a hard pull |
| Funding | Most get a same-day decision and can be funded the day they sign |
| Eligibility | Wells Fargo customer for at least 12 months, plus other requirements |
JustMobs rating: 4.3/5. Excellent terms held back only by the customer-tenure requirement.
Rates: what the range really means
Wells Fargo’s lowest advertised APR, 6.74%, comes with conditions. It applies to loans of at least $10,000 with a three-year term, and it assumes excellent credit. The bank says at least 10% of approved applicants received the lowest rate between April 1 and June 30, 2026, which tells you the bottom of the range is reachable but far from typical.
The top of the range, 26.74%, is the more telling number. Many online lenders go up to 35.99%. A lower ceiling means Wells Fargo is pickier about who it approves, but also that even approved borrowers with average credit won’t see the highest subprime prices.
The displayed rates include a 0.25% relationship discount. To get it, you need a Wells Fargo consumer checking account and automatic payments from a Wells Fargo deposit account. If you cancel autopay later, your rate and payment may go up.
Wells Fargo’s own example: $17,000 over 48 months at a 13.99% APR is about $464 a month, assuming on-time payments.
Fees: almost none
No origination fee is the headline advantage over online lenders. Compare it with a fair-credit lender charging 8% upfront: on a $20,000 loan, that’s $1,600 you’d never see. With Wells Fargo, the full amount you borrow reaches you, and there’s no closing fee or prepayment penalty either. Late fees can still apply.
Terms and loan size
Seven term options from one to seven years give you real control over the payment. A 12-month term suits a short-term need you can clear quickly; 84 months can make a large consolidation or home project affordable month to month, though you’ll pay more interest overall. Loan amounts up to $100,000 are among the highest anywhere for an unsecured personal loan.
Speed
Wells Fargo says most customers get a same-day credit decision and can receive funds the day they sign, and that 97% of customers received funds on the day they signed in April through June 2026. Being an existing customer helps here: the bank already knows you, and the money can land directly in your Wells Fargo account.
Pros and cons
- Pro: No origination, closing or prepayment fees
- Pro: APR ceiling far below most online lenders
- Pro: Up to $100,000 and up to 84 months
- Pro: Same-day funding is the norm for approved borrowers
- Con: Must be a Wells Fargo customer for 12 months or more
- Con: Lowest rates need strong credit, $10,000 or more and a three-year term
- Con: Losing autopay can raise your rate
How it stacks up against U.S. Bank and Citi
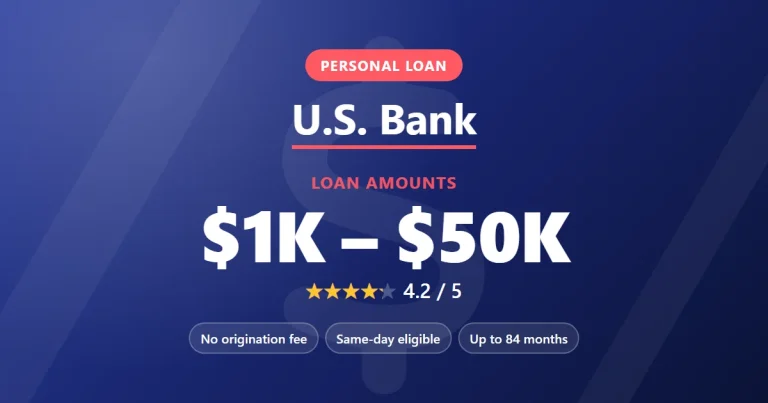
The U.S. Bank personal loan is more open: non-customers can borrow up to $25,000 on terms up to 60 months, while customers can get $1,000 to $50,000 and up to 84 months. Its APR range as of September 2026 ran from 9.24% to 24.99%. Wells Fargo offers a lower floor and twice the maximum loan, but only to established customers.
The Citi personal loan has an unusually narrow APR range (10.24% to 18.49% as of late September 2026) and no origination or late fees, but loans top out at $30,000 for most applicants and $50,000 for eligible existing customers. For a big loan with a strong credit profile, Wells Fargo usually comes out ahead; for a mid-size loan, check all three.
Is it worth applying?
If you’ve been a Wells Fargo customer for at least a year and have good credit, yes. Check your rate first. It’s a soft pull, and you’ll see whether the offer beats what you’d get from an online lender. The absence of fees means the APR comparison is apples to apples: Wells Fargo’s APR is essentially its interest rate.
If you’re not a customer, this loan isn’t an option right now, and opening an account just to qualify a year from now rarely makes sense unless you wanted the account anyway. Look at banks with fewer restrictions, or a credit union.
If your credit is fair and you’re a customer, still check. The worst case is a decline after a soft pull, which doesn’t touch your score.
To check your rate, visit Wells Fargo’s personal loan page. Rates and terms are as of 2026 and can change without notice.
Frequently asked questions
Does a Wells Fargo credit card count toward the 12-month customer requirement?
Wells Fargo states the rule as being a customer for at least 12 months and meeting other requirements, without spelling out every account type on its main page. The relationship discount, though, specifically requires a consumer checking account. Ask a banker or start the rate check to confirm your eligibility.
Can I use the loan to pay off credit cards?
Yes. Consolidation is a common use. Before you do, read the Consumer Financial Protection Bureau’s guidance on consolidating credit card debt, especially the warning about longer terms costing more overall.
Will the hard inquiry hurt my score much?
A single hard inquiry usually has a small, temporary effect. It only happens when you submit the full application, not when you check rates.
What if I stop autopay after the loan closes?
You’d lose the 0.25% relationship discount, and Wells Fargo says your rate and monthly payment may increase as a result.