Picture a borrower we’ll call Dana. This is a hypothetical example, not a real customer. Dana carries $19,000 across three credit cards, all charging well over 20%, and juggles three due dates every month. She wants one fixed payment with an end date.
She checks her rate with Achieve and gets a hypothetical offer: a $20,000 loan over 48 months at a 15% interest rate with a 5% origination fee. The fee comes out of the loan before it’s funded, so $1,000 is deducted and $19,000 lands where it needs to go, enough to clear the three cards. Her new payment works out to roughly $557 a month for four years, and the total repaid is about $26,700.
Is that a good trade? It depends on what Dana was doing before. If she was paying only the minimums on 24% cards, the cards could have dragged on for many years and cost more in interest. If she could have attacked them aggressively in two years, the loan might not save much. That is the right lens for every consolidation loan, Achieve’s included: compare the total cost and the payoff date, not just the monthly number.
Key takeaways
- Achieve offers fixed-rate loans from $5,000 to $50,000 with APRs from 6.25% to 35.99% and terms of two to five years, as of 2026.
- There’s an origination fee of 1.99% to 9.99%, deducted from your loan proceeds, and no prepayment penalty.
- Three discounts can lower your rate: adding a co-borrower, letting Achieve pay creditors directly, and showing retirement savings.
- Checking your rate is a soft pull. The stated minimum credit score is 560, or 660 for consolidation loans of $35,000 or more.
JustMobs rating: 4.2/5.
What Achieve is
Achieve is a consumer finance company built around debt: it offers personal loans, home equity products and a debt resolution program. The personal loan is the piece most people find through a consolidation search, and it’s designed for exactly that job. You can use it for other purposes, but the rate discounts and the direct-pay feature only make full sense when you are paying off existing balances.
The three rate discounts
This is what separates Achieve from a plain-vanilla online lender. According to Achieve, members have cut their rate by up to 4% using these discounts, though your result depends on your file.
Co-borrower
Applying with a co-borrower who has solid credit and income can lower your price. That person shares full legal responsibility for the loan, so this works best between spouses or partners who already share finances.
Direct pay to creditors
If you let Achieve send the money straight to your card issuers or other creditors, you can earn a lower rate. Lenders like this because it guarantees the money goes to debt payoff. You benefit from the discount and from not having the cash sitting in your checking account, tempting you.
Retirement savings
Showing that you have money in a 401(k), IRA, Roth IRA or TSP can also lower your rate. You aren’t pledging those accounts as collateral; the balance is treated as a sign of financial stability. This is unusual. Most lenders ignore retirement assets entirely.
Costs and fine print
Achieve’s APR range runs from 6.25% to 35.99%, a wide spread that tells you underwriting matters a lot. The low end requires strong credit and, typically, one or more of the discounts. Borrowers near the 560 minimum should expect offers toward the top of the range.
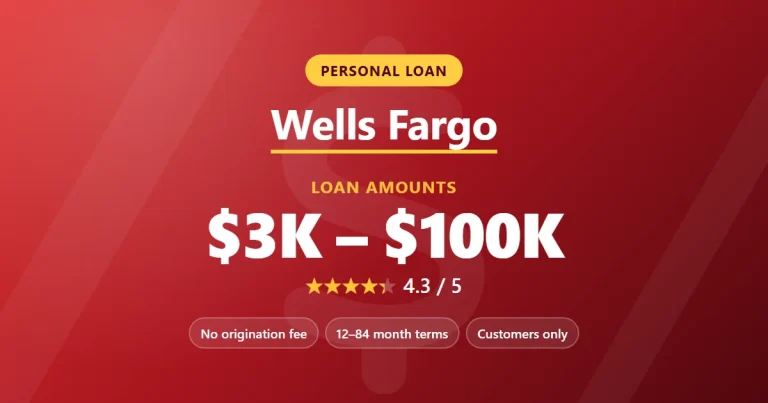
The origination fee of 1.99% to 9.99% is the main drawback. On a $30,000 loan, a 9.99% fee means nearly $3,000 never reaches you. Because the fee is deducted up front, you have to borrow more than your debt total to cover it, as Dana did in the example above. Lenders such as Wells Fargo and Citi charge no origination fee, but they’re narrower in who they lend to.
Funding is quick, though not instant. Achieve’s page says funds are typically sent within 24 to 72 hours, and in its step-by-step description, as little as one to three days after approval. Direct payments to creditors can take longer to post on their end.
Rate checks are soft pulls and take a couple of minutes. The full application triggers a hard inquiry.
How it compares with Happy Money
Happy Money is the closest rival: it also targets credit card payoff, lends $5,000 to $50,000, and charges an origination fee. The differences come down to features. Happy Money’s advertised rates assume autopay and its loans are originated by partner banks. Achieve offers the stacked discounts described above, plus a stated minimum credit score, so you know where the floor is. If you have retirement savings or a co-borrower, Achieve’s structure gives you more ways to reduce your rate. If neither applies, check both and take the lower APR.
Strengths and weak spots
Achieve earns its rating with a lender model that rewards responsible behavior. The direct-pay discount nudges borrowers toward actually using the loan to clear debt, which is the point. Loan sizes up to $50,000 cover most consumer debt loads. Terms of two to five years keep you from stretching a balance out forever.
On the downside, the origination fee can be steep, there’s no option for terms longer than five years if you need a smaller payment, and the $5,000 minimum rules it out for small balances. The 660 score requirement for consolidation loans of $35,000 or more also limits the biggest loans to borrowers with decent credit.
One caution unrelated to Achieve itself: consolidation only works if the cards stay paid down. The Consumer Financial Protection Bureau notes that a consolidation loan probably won’t help if you keep spending more than you earn. Clearing your cards also lowers your credit utilization, which myFICO lists among the biggest score factors, so running the balances back up undoes that benefit too.
The verdict
Achieve is one of the better choices for a mid-size or large consolidation loan if you can use at least one of its discounts. The direct-pay and retirement-savings discounts are real advantages that few competitors match, and a 560 minimum score makes it reachable for borrowers rebuilding credit. Just run the math on the origination fee before you accept. If your credit is strong and you bank with a large institution, a no-fee bank loan may still come out ahead.
You can check your rate without affecting your score on Achieve’s personal loan page. Rates, fees and discounts are as of 2026 and can change.