“I’ve had a Citi checking account for years and I want to pay off about $12,000 on two cards from other banks. Citi says its loan has no fees. Is there a catch?”
There’s no hidden fee catch, as far as Citi’s published terms go. The real catches are about who qualifies and which debts you can pay off with it. For a long-time Citi customer with good credit and non-Citi card balances, like the reader above, this is one of the cleaner personal loans on the market.
Key takeaways
- As of September 29, 2026, Citi’s APRs run from 10.24% to 18.49%, with no origination fee, no late fees and no prepayment penalty.
- Most applicants can borrow $2,000 to $30,000; existing customers with an eligible Citi deposit account or Citi credit card may qualify for up to $50,000.
- Funds deposited to a Citi account usually arrive the same business day; external accounts take up to two business days.
JustMobs rating: 4.1/5.
The rate range is the story
An APR range of 10.24% to 18.49% is unusually narrow. Most lenders stretch to 25% or 35.99%, which signals they’re willing to approve riskier borrowers at high prices. Citi’s ceiling says the opposite: it lends mainly to borrowers with solid credit and prices them in a tight band.
The bottom of the range has conditions. The lowest rate assumes excellent credit, a 36- or 48-month term and Citi’s autopay discount, which knocks 0.25% off your APR if you enroll in automatic payments when the loan is opened. Plan for a rate somewhere in the middle unless your credit is exceptional.
For the reader with $12,000 on cards, the math is attractive if the cards charge more than 20%. Even an offer near Citi’s ceiling would cut the rate, and with no origination fee, all $12,000 goes to the balances.
Fees: genuinely minimal
Citi’s page lists no origination fees, no late fees and no prepayment penalty. Citi does say it will disclose any applicable fees when you apply, so read your loan agreement. Still, the lack of a late fee is rare. It doesn’t make paying late harmless, since late payments can be reported to the credit bureaus, but it removes one penalty most lenders charge.
Eligibility and the fine print
Citi’s rules are more specific than most:
- You must be at least 18 (21 in Puerto Rico).
- Co-applicants are not permitted. You qualify on your own credit and income.
- Citi credit card customers who have been Citi customers for less than 12 months and don’t have a Citi deposit account are not eligible.
- The higher $50,000 limit requires an eligible Citi checking or savings account or a Citi credit card.
There’s also an important restriction on debt consolidation. Citi-issued credit cards, Checking Plus and Ready Credit accounts can’t be paid off with the loan, and Citi won’t issue payoff checks for them. If most of your debt is on a Citi card, this loan won’t help you consolidate it. Our reader is fine, since both cards are from other banks.
Funding speed
Citi says most approved applicants get funds the same business day when the money goes into a Citi account. Deposits to an outside bank account take up to two business days, and a mailed check takes about five business days. Checking your rate first is a soft inquiry; the full application is a hard inquiry.
How Citi compares with Wells Fargo
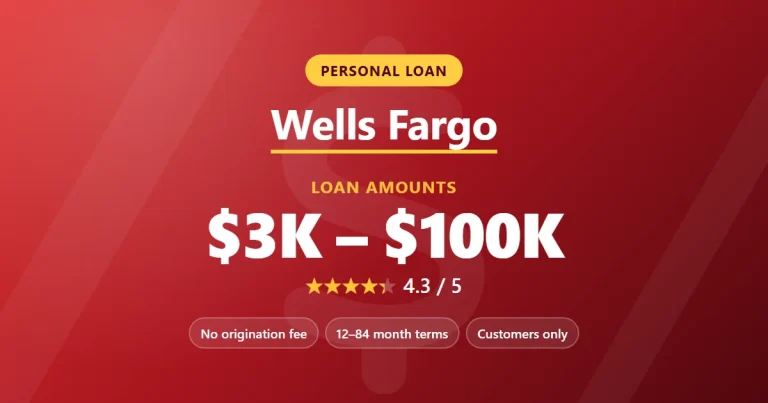
The closest rival is the Wells Fargo personal loan, another no-origination-fee loan for existing customers. Wells Fargo’s APR range is wider (6.74% to 26.74% as of July 2026), so its very best rate is lower than Citi’s, and it lends up to $100,000 on terms up to 84 months. Citi’s ceiling is far lower, though, so a borrower with merely good credit might get a better deal at Citi. Citi also skips late fees, which Wells Fargo may charge. Wells Fargo requires 12 months as a customer across the board; Citi’s 12-month rule applies specifically to card-only customers.
The U.S. Bank personal loan is the more flexible choice if you need longer terms or want to add a joint applicant, which Citi doesn’t allow.
Strengths and drawbacks
Strengths: a low APR ceiling, no origination or late fees, fast funding to Citi accounts, a soft-pull rate check and higher limits for loyal customers. Drawbacks: no co-applicants, terms generally limited to 12 to 60 months, a $30,000 cap for most applicants and the ban on paying off Citi’s own credit products. Borrowers with fair credit will likely find the approval standards tough.
Who should apply
The Citi personal loan fits borrowers with good to excellent credit who already bank with Citi, especially those consolidating card debt held at other issuers. It’s also a good fit for anyone who wants a no-fee loan funded quickly and can manage the payment on a term of five years or less.
Look elsewhere if you need a co-borrower to qualify, need more than $50,000, want a seven-year term, have fair credit, or carry most of your debt on Citi cards. A Citi balance transfer offer, if you qualify, might be the better tool for Citi card debt.
Before consolidating, it’s worth reading the Consumer Financial Protection Bureau’s notes on what to know about consolidating credit card debt. Then check your rate on Citi’s personal loan page. Rates and terms are as of 2026 and can change at any time.
Common questions
Who actually makes the loan?
Citibank, N.A. makes the loans directly. There’s no third-party lending partner involved.
Can I pay off a Citi credit card with a Citi personal loan?
No. Citi-issued cards, Checking Plus and Ready Credit accounts aren’t eligible for debt consolidation with this loan.
Does checking my rate affect my credit?
No. The rate check is a soft inquiry. A hard inquiry happens only when you submit a full application.
How do I get the autopay discount?
Enroll in automatic payments when the loan is originated. Citi applies a 0.25% APR reduction for doing so.