OneMain Financial makes the most sense for one kind of borrower: someone with fair or thin credit who needs a few thousand dollars, has been declined (or priced out) by online lenders, and would rather sit across a desk from a loan specialist than upload documents into a portal. If that describes you, OneMain is worth a look. If you have good credit and shop mainly on price, you will almost certainly find a cheaper loan elsewhere.
That split is the whole story with this lender. OneMain approves people that banks and many fintechs won’t, and it backs that with a large physical branch network. The price of that flexibility is high APRs and, in many states, an origination fee.
OneMain at a glance
| Feature | What OneMain offers (as of 2026) |
|---|---|
| Loan amounts | $1,500 to $30,000 |
| Repayment terms | 24 to 60 months |
| APR | Fixed; tops out at 35.99%, and is generally higher on loans not secured by a vehicle |
| Origination fee | Where state law allows: a flat $25 to $500, or 1% to 10% of the loan amount |
| Prepayment penalty | None |
| Secured option | Yes; larger amounts require a first lien on a vehicle no more than 10 years old |
| Joint applications | Yes |
| Prequalification | Soft credit pull; no effect on your score |
| Funding | Advertised as soon as one hour after signing, for eligible borrowers |
JustMobs rating: 3.8/5. Strong on access and service, weak on cost.
How a OneMain loan actually works
You start online by checking for offers. OneMain runs a soft inquiry for this step, so your credit score is untouched. If you see an offer you like, the process usually moves to a conversation with a loan specialist, and many borrowers finish at a local branch where they verify income and identity and sign. When you formally apply, OneMain does a hard pull, which can shave a few points off your score for a while.
The branch step is the feature most competitors lack. If your income is irregular, you are self-employed, or your credit report has a story that needs explaining, a human reviewer can weigh that context. Online lenders mostly rely on automated decisions, which is fine until your file doesn’t fit the model.
Secured versus unsecured
OneMain lets you put up a car, truck or similar vehicle as collateral. According to its disclosures, larger loan amounts require a first lien on a motor vehicle no more than ten years old that meets its value requirements and is titled in your name with valid insurance. Securing the loan can get you approved for more money, or at a lower APR than you would get unsecured.
The trade-off is serious. Miss enough payments and OneMain can repossess the vehicle. If losing your car would also mean losing your way to work, think hard before pledging it for a consolidation loan or a vacation.
Adding a co-borrower
Joint applications are allowed, and checking offers with a co-borrower is still a soft pull. The second person has to meet OneMain’s eligibility rules and may need to show the same proof-of-income documents as you. A co-borrower with steadier income can make the difference between a decline and an approval, but they are fully on the hook for the debt.
What it really costs
OneMain’s maximum APR of 35.99% is the same ceiling most subprime-friendly lenders use. Where you land depends on your credit, income, existing debts, state of residence and whether the loan is secured. OneMain does not publish a minimum credit score, so you only learn your price by checking.
The origination fee deserves attention. It varies by state: some states allow a flat fee from $25 to $500, others a percentage from 1% to 10% of the loan. OneMain typically finances the fee as part of the loan, which means you pay interest on it for the whole term. On a small loan, a flat $500 fee can push the effective cost well above the stated interest rate, so always compare the APR on your offer, not just the monthly payment.
There’s no prepayment penalty. If you can pay the loan off early, you save the remaining interest, which is the best way to blunt a high rate.
Pros and cons in plain terms
What OneMain does well:
- Approves borrowers with fair or damaged credit who are often declined elsewhere
- In-person help at local branches, plus a phone and online process
- A secured option that can raise your approval odds or loan size
- Joint loans, which many online lenders don’t offer
- Fast funding once the loan is signed
Where it falls short:
- High APRs; borrowers with good credit can usually do better
- Origination fees in many states, financed into the balance
- A $30,000 ceiling, lower than many online lenders
- Secured loans put your vehicle at risk
- No published minimum credit score, so you can’t gauge your odds before checking
Who should skip it
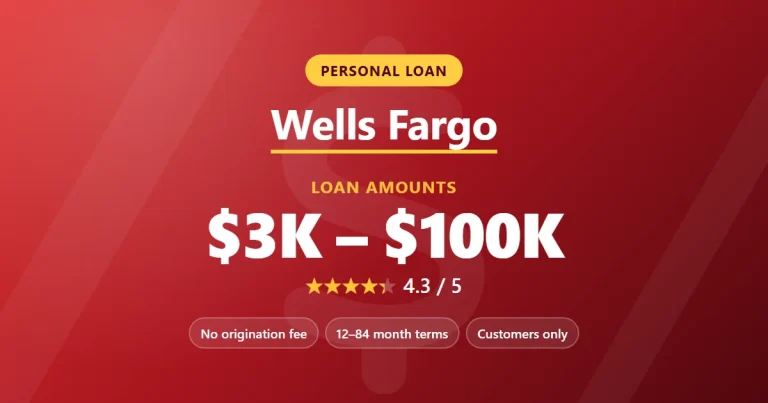
If your credit score is in the 700s and your debt-to-income ratio is reasonable, a bank or credit union loan will usually cost far less. Existing customers of big banks should check offers like the Wells Fargo personal loan, which has no origination fee and a much lower APR ceiling. Also skip OneMain if the purpose is discretionary. A 30%-plus APR loan for a purchase you could save for in a few months is rarely a good deal.
Before you borrow to consolidate, read the Consumer Financial Protection Bureau’s guidance on consolidating credit card debt. A lower monthly payment over a longer term can still cost more in total.
Alternatives to compare
OneMain competes most directly with other lenders that serve fair credit. Two worth putting side by side:
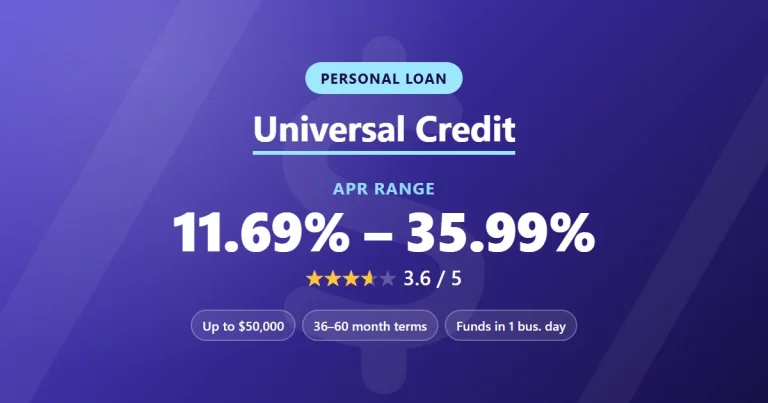
- Universal Credit: an online-only brand of Upgrade with loans up to $50,000 and terms of 36 to 60 months. No branches, but a higher maximum loan and a lending model built for fair credit. Its origination fee runs 5.25% to 9.99%, so compare total cost carefully.
- Reach Financial: online loans from $3,500 to $40,000 with origination fees of 0% to 8%, aimed largely at debt consolidation.
Prequalify with OneMain and at least one online lender on the same day. Since all of them use soft pulls for the first look, comparing costs you nothing, and the APRs can differ by several points for the same person. You can check offers on OneMain’s personal loan page. Rates, fees and terms can change, so confirm everything in your loan agreement before you sign.
Frequently asked questions
Do I have to visit a branch to get a OneMain loan?
Not always. Much of the process can be handled online and by phone, but OneMain’s model leans on branch staff, and some borrowers are asked to come in to verify documents or close. If you prefer a fully digital lender, that’s a reason to compare online options first.
Will checking my rate hurt my credit?
No. Checking for offers uses a soft inquiry. The hard inquiry happens only when you move forward with a full application.
Can I use a car I’m still paying off as collateral?
OneMain requires a first lien on the vehicle, so a car with an existing auto loan generally won’t qualify unless that lien is cleared. The vehicle also has to be ten years old or newer, titled in your name and insured.
Is the origination fee charged in every state?
No. OneMain charges it only where permitted by law, and the amount and method (flat or percentage) depend on your state. Your loan documents will show the exact figure before you sign.